
TL;DR
- FHA loans work with small down payments and lower credit scores but carry mortgage insurance you usually can't cancel; conventional loans let you drop PMI once you reach 20% equity.
- A $190,000 loan at 6.75% runs about $1,233/month in principal and interest. At 6.25% it's about $1,170, a difference of roughly $22,700 over 30 years.
- Budget 2% to 3% of your loan amount for closing costs on top of your down payment. On a $190,000 loan that's $3,800 to $5,700 in cash at the table.
- Most Metro Detroit lenders we see cap total debt payments (DTI) around 43-45% of gross monthly income. That ceiling, not the list price, is usually what limits your budget.
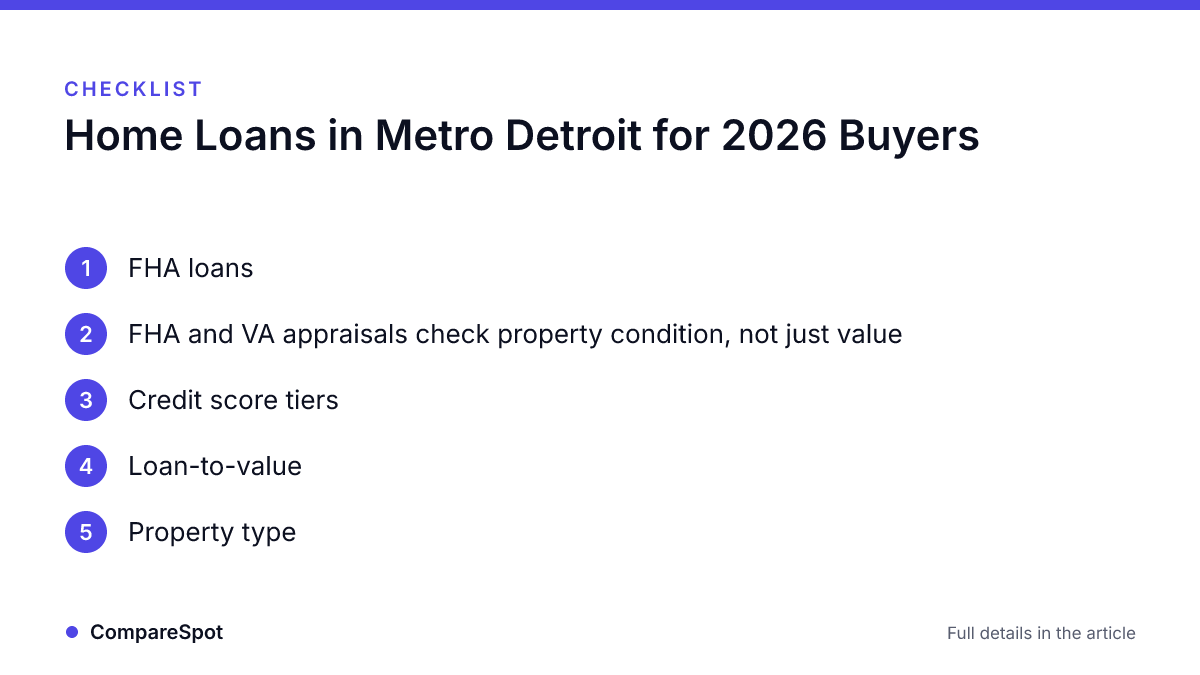
- FHA and VA appraisals check property condition, not just value, which matters enormously in a market full of pre-1960 housing. Expect extra weeks if repairs get flagged.
A home loan is money a bank, credit union, or mortgage company lends you to buy a house, repaid over 15 or 30 years with interest. Simple enough. The part that actually decides your monthly payment in Metro Detroit is which loan type you use, because FHA, conventional, VA, and USDA each change your down payment, your mortgage insurance, and how picky the appraiser gets about that 1952 bungalow in Royal Oak with the soft spot over the garage.
We've spent years comparing lenders and loan products for buyers across Wayne, Oakland, and Macomb counties. The same confusion shows up every time: people assume one loan type is universally better. It isn't. The right answer comes down to your credit, your savings, and the condition of the house.
Table of Contents
- What is the difference between FHA and conventional loans?
- How do mortgage rates compare across loan types in Metro Detroit?
- What closing costs should you budget for beyond your down payment?
- How do Detroit lenders decide if you qualify?
- Do appraisal rules differ between loan types?
- Is a home equity loan the same as a home loan?
- Where should first-time buyers in Michigan start?
- Frequently asked questions
What is the difference between FHA and conventional loans?
FHA loans are government-insured, allow very small down payments, and tolerate lower credit scores, but they come with mortgage insurance that typically sticks around for the life of the loan. Conventional loans aren't government-backed, want stronger credit, and let you cancel private mortgage insurance once you hit 20% equity. HUD-approved counselors walk through the FHA vs. conventional loan comparison for free if you want a second opinion before you commit.
Here's where it bites in Detroit. A large share of the city's housing stock predates 1960, and FHA appraisers flag peeling paint, missing handrails, and a roof near the end of its life in ways conventional appraisers usually don't. Good protection if you're buying a fixer. Deal-killing if the seller has no cash to make repairs before closing and no interest in finding any.
| Loan type | Down payment lenders typically ask for | Credit score we typically see required | Mortgage insurance | Best fit |
|---|---|---|---|---|
| Conventional | 3% to 20% | Around 620 and up | PMI, cancellable at 20% equity | Decent credit, some savings, house in solid shape |
| FHA | 3.5% | Around 580 and up | MIP, usually for the life of the loan | First-time or lower-credit buyers |
| VA | 0% | No program minimum; lenders set their own | None, but a funding fee applies | Eligible veterans and service members |
| USDA | 0% | Around 640 | Annual guarantee fee | Outlying areas beyond Detroit's urban core |
Pro tip: If you're a first-time buyer putting down less than 10%, make your loan officer price the deal both ways and hand you two Loan Estimates. Michigan down payment assistance can swing the math toward conventional, because dodging FHA's permanent mortgage insurance often beats the slightly lower FHA note rate. We cover the state and local options in our guide to first-time home buyer programs in Michigan.
How do mortgage rates compare across loan types in Metro Detroit?
Rates move with the bond market every day, so there's no fixed "Detroit rate." The pattern we see is steady, though: FHA and VA note rates usually quote a little lower than conventional, and mortgage insurance often eats that advantage before the first payment is due. Compare total monthly cost, not the rate on the flyer.
What actually moves your personal rate:
- Credit score tiers: Pricing changes in bands, not smoothly. Going from 659 to 660 can be worth more than going from 700 to 739, which is why fixing a tradeline before you apply pays off.
- Loan-to-value: Less money down means more lender risk and a small rate bump, with the breakpoints usually falling at 80%, 85%, 90%, and 95% LTV.
- Property type: Condos and two-to-four-unit buildings carry add-ons that a standalone single-family doesn't.
- Points: Buying down the rate makes sense if you'll hold the loan seven-plus years. Divide the cost of the points by the monthly savings to get your break-even month, then be honest about whether you'll still be there.
- Term: 15-year loans price lower than 30-year loans and hurt a lot more each month.
Big national banks, Michigan credit unions, and local brokers all compete hard for Metro Detroit business, and quotes for the identical borrower profile can land further apart than people expect. Collect three to five quotes on the same day, since a Tuesday quote and a Friday quote aren't comparable. Then put the Loan Estimates side by side and compare page 2 line for line. Origination fee, discount points, and lender credits are where the real differences hide. An online mortgage calculator is fine for a sanity check, but it doesn't know what any lender will actually charge you.
Show the math: On a $190,000 loan at 6.75% fixed for 30 years, principal and interest is about $1,233 a month. The formula: monthly payment = loan amount × monthly rate × (1 + monthly rate)^360 ÷ [(1 + monthly rate)^360 − 1], where the monthly rate is your annual rate divided by 12. Run the same loan at 6.25% and the payment drops to roughly $1,170. That's $63 a month, or about $22,700 across the full term. Re-run it with your own loan amount before you decide one quote is "close enough" to another.
What closing costs should you budget for beyond your down payment?
Plan on 2% to 3% of your loan amount in closing costs, separate from the down payment. On a $190,000 loan that's $3,800 to $5,700 in cash due at closing, covering lender fees, title insurance, recording fees, prepaid property taxes, and a year of homeowners insurance up front.
FHA adds an upfront mortgage insurance premium that almost always gets financed rather than paid in cash. As an illustration, at the 1.75% rate lenders have been quoting, a $193,000 FHA loan picks up about $3,377 in upfront MIP. You don't write a check for it, but you pay interest on it for three decades.
| Loan type | Upfront fee | Cash at closing or financed? |
|---|---|---|
| Conventional | None; PMI is billed monthly | Not applicable |
| FHA | Upfront MIP, commonly quoted at 1.75% of the loan | Usually financed into the balance |
| VA | Funding fee, scaled by down payment and prior use | Can be financed |
| USDA | Upfront guarantee fee | Usually financed |
Title and escrow charges deserve their own look before you sign anything. We break them down in our piece on title company fees in Metro Detroit, and buyers should read our guide to buyer closing costs before shopping lenders. On plenty of deals we've compared, the title company moved the bottom line more than the loan type did.
How do Detroit lenders decide if you qualify?
Three things carry most of the weight: credit score, debt-to-income ratio, and income stability. Most conventional lenders we work with cap DTI around 43-45%. FHA will sometimes stretch past that when the file has strong compensating factors like cash reserves or a long history at the same employer.
The math is straightforward. Add up your gross monthly income. Add up your minimum monthly debt payments, including the new mortgage. Divide debts by income.
Show the math: You earn $5,000/month gross and pay $600/month toward a car loan and credit card minimums. At a 45% cap, total allowed debt is $5,000 × 0.45 = $2,250. Subtract the existing $600 and you have $1,650 left for the entire housing payment: principal, interest, property taxes, homeowners insurance, PMI, and any HOA dues. In the Detroit area, taxes and insurance frequently run $400 to $600 of that, which leaves far less for principal and interest than buyers expect. That $1,650 ceiling, not the asking price, is your real budget.
Four qualification realities worth knowing before you apply:
- A 620 score doesn't lock you out. It rules out most conventional pricing, FHA stays wide open, and some credit unions and portfolio lenders go lower when income and reserves are solid.
- Self-employed and 1099 income usually needs two years of tax returns, and underwriters average the net income after write-offs. Contractors and rideshare drivers who deduct aggressively get surprised by how small their qualifying income looks.
- Recent job changes aren't fatal, but moving from salary to commission, or switching industries, slows underwriting while they document your history.
- Reserves punch above their weight. Two to six months of mortgage payments left in savings after closing can offset a weaker DTI or a thinner credit file.
Pro tip: Pull your own credit before any lender does, and dispute errors first. We've watched a single incorrect $90 medical collection drag a score below a pricing tier and cost a buyer real money every month for no reason at all.
Do appraisal rules differ between loan types?
Yes, and this derails more Metro Detroit deals than anything else in the file. FHA and VA appraisals include a condition review, the Minimum Property Requirements check on the FHA side, that flags safety and habitability problems: exposed wiring, missing handrails, chipping paint on a pre-1978 house, a roof with little life left. Conventional appraisals mostly care about value.
In Detroit, Pontiac, and older pockets of Madison Heights, that difference shows up constantly. In the files we've followed, a flagged repair plus a re-inspection typically adds one to three weeks to the timeline, and it spooks sellers who wanted a fast close. The workaround experienced agents use: get the repairs priced before the appraisal order goes in, and negotiate who pays while you still have leverage, not after the appraiser hands you a conditional report.
If you're buying or inheriting a property that can't clear an FHA appraisal without serious work, selling to a cash buyer sometimes beats fighting the financing. And if the house came through probate, our guide to selling an inherited house in Detroit walks through the extra steps. For a feel for what financed buyers are actually landing right now, our guide to what $200K buys in Detroit is worth reading before you set a budget.
Is a home equity loan the same as a home loan?
No. A home equity loan is a second loan against a house you already own, not financing to buy one. You borrow against built-up equity, usually as a lump sum at a fixed rate, while your original mortgage stays in place.
The two get lumped together because people say "home loans" for both. Say you own a Royal Oak bungalow worth $300,000 with $160,000 left on the mortgage. Most lenders will let you borrow up to roughly 80-85% of value combined, so at 85% that's $255,000 total, minus your $160,000 balance, leaving about $95,000 available. Whether you'd be approved for all of it still depends on your DTI with both payments counted.
A HELOC is the more flexible cousin: you draw what you need instead of taking the whole sum and paying interest on money sitting in your checking account. For a kitchen where the final bill is anyone's guess, the line usually beats the lump sum. Landlords lean on these to fund repairs rather than raising rent mid-lease. If that's you, our breakdown of property management companies in Metro Detroit covers who handles that maintenance coordination.
Where should first-time buyers in Michigan start?
Get preapproved, not prequalified. Preapproval means a lender verified your income, assets, and credit. Prequalification means you told someone your income over the phone. Metro Detroit listing agents know the difference, and in a multiple-offer situation it decides which file gets read first.
A realistic sequence:
- Check your credit and pay down revolving balances two to three months before applying, since card balances under 30% of the limit move scores fastest.
- Get preapproved with two to three lenders and compare actual Loan Estimates rather than advertised rates.
- Research Michigan down payment assistance, which stacks with FHA on many first-time buyer deals and can cover most of the 3.5% down.
- Budget the full cash to close, down payment plus closing costs plus prepaids, so nothing blindsides you the week of signing.
- Hire your own inspector even on a conventional loan. The appraisal is not an inspection and never was.
Once you've closed, furnishing an older house on what's left of your savings is its own project. Our roundup of furniture stores in Metro Detroit and best used furniture shops in Detroit covers the budget end without defaulting to big-box particleboard.
Frequently asked questions
Can I get a home loan with bad credit in Detroit?
Yes, with fewer options. FHA is the usual landing spot for scores in the 500s and low 600s, and some local credit unions and portfolio lenders will work with weaker credit when income and reserves are strong. You'll pay a higher rate than a borrower with excellent credit. If your timeline allows three to six months of cleanup first, that's often the highest-return work you can do.
How long does mortgage preapproval take in Metro Detroit?
Most lenders issue a preapproval letter within 24 to 72 hours once they have pay stubs, bank statements, and tax returns in hand. Full underwriting after you're under contract usually runs two to four weeks. Self-employed borrowers and anyone with rental income, commission, or multiple jobs should plan on the long end.
Is it better to use a bank, credit union, or mortgage broker for a home loan?
There's no universal winner. Banks carry the widest product menu, credit unions often price better for members and keep fees low, and brokers shop several wholesale lenders for you. Get a quote from one of each on the same day and compare total cost over the time you'll realistically own the house, not the headline rate.
Want help finding other vetted Metro Detroit service providers for your move? See how we research our rankings on our about page, get in touch with a question about your situation, or browse the full blog for more local real estate guides. Before anything else, though, pull your credit report this week. Everything downstream prices off that number.